A book by Moise (MO) Phanor
The Biased Buyer
Know what you want before someone tells you what you can afford.
Most people learn how mortgages work while they are being sold one. This book fixes that order. It gives you the mindset, the vocabulary and the questions before you walk into the conversation — so the decision stays yours.
As featured in
- The Morning Ledger
- Homefront Weekly
- Main & Market
- The Closing Table
- Rate & Reason
The core idea
Five pillars of the mortgage mindset
You decide before you shop.
Most buyers form their opinion of what they can afford in a lender's office. By then the frame is already set for them.
The payment is the product.
You do not buy a rate. You buy a monthly obligation that includes taxes, insurance and upkeep. Price the whole thing.
Approval is a ceiling, not a target.
Qualifying for an amount is a statement about risk models. It is not a recommendation about your life.
Fit beats the headline number.
The cheapest advertised rate often comes from the shop least equipped to understand an unusual file. Match the lender to your situation.
Your bias has a price tag.
Anchoring, urgency, and the fear of missing out all show up in the paperwork. Name them and they lose most of their power.
From the book
The decision is made long before the paperwork
Here is the sequence almost every buyer follows. You wonder if you can afford a home. You call a lender. The lender runs numbers and hands you a figure. From that moment on, every house you look at is measured against a number a stranger produced in eleven minutes.
That number is not wrong, exactly. It is just answering a different question than the one you care about. It answers: what is the largest loan a model is comfortable issuing you? You wanted to know: what is a payment I can live with for the next decade, in a life that will change?
Anchoring is not a personality flaw
Anchoring means the first number you hear quietly sets the range for everything that follows. It is not a sign of weak willpower. It happens to careful people, to analysts, to people who negotiate for a living. The only reliable defense is to bring your own number first.
Before your first call, write down two figures: the monthly payment you would be content with, and the monthly payment that would make you anxious. Those two numbers are your range. When a pre-approval letter arrives with a bigger figure on it, you will notice it as information rather than absorbing it as a goal.
“A pre-approval tells you what a lender is willing to risk. It says nothing about what you should be willing to carry.”
Urgency is a sales tool
Someone will tell you the market is about to move. They may be right. They are also describing a condition that has existed continuously for as long as there have been markets. Urgency is real, but it is also the most common lever used on buyers, and it works because it shortens the window in which you think.
The counter is not stubbornness. It is preparation. If your criteria are written down before the pressure arrives, you can move quickly without moving carelessly. Speed and clarity are not opposites — clarity is what makes speed safe.
What a good conversation sounds like
A good lender conversation is boring in the best way. You describe how you get paid. They tell you which programs fit and which do not. You ask what would make your file fall apart, and they answer honestly instead of reassuring you. Nobody mentions a rate in the first ten minutes.
If that sounds unrealistic, that is the gap this book is trying to close. Not by making you an expert in underwriting, but by making you a buyer who knows what they came for.
Readers
What people say after reading it
“I read this two weeks before our first lender call and it completely changed the questions I asked. We ended up in a better loan and a smaller payment than we planned for.”
 Daniela ReyesFirst-time buyer, Orlando
“I hand this to every client before we tour a single house. It saves us a month of confusion and it makes them a much calmer buyer.”
 Mark EllisonReal estate broker
“Finally a book about mortgages that respects the reader. No rate hype, no jargon dumps, just clear thinking about a decision most of us only make twice.”
 Grace LimFinancial coach
Free, 3 minutes
Every buyer is biased in a different direction. Which one are you?
Order
Get your copy
Available in hardcover, paperback, ebook and audio.
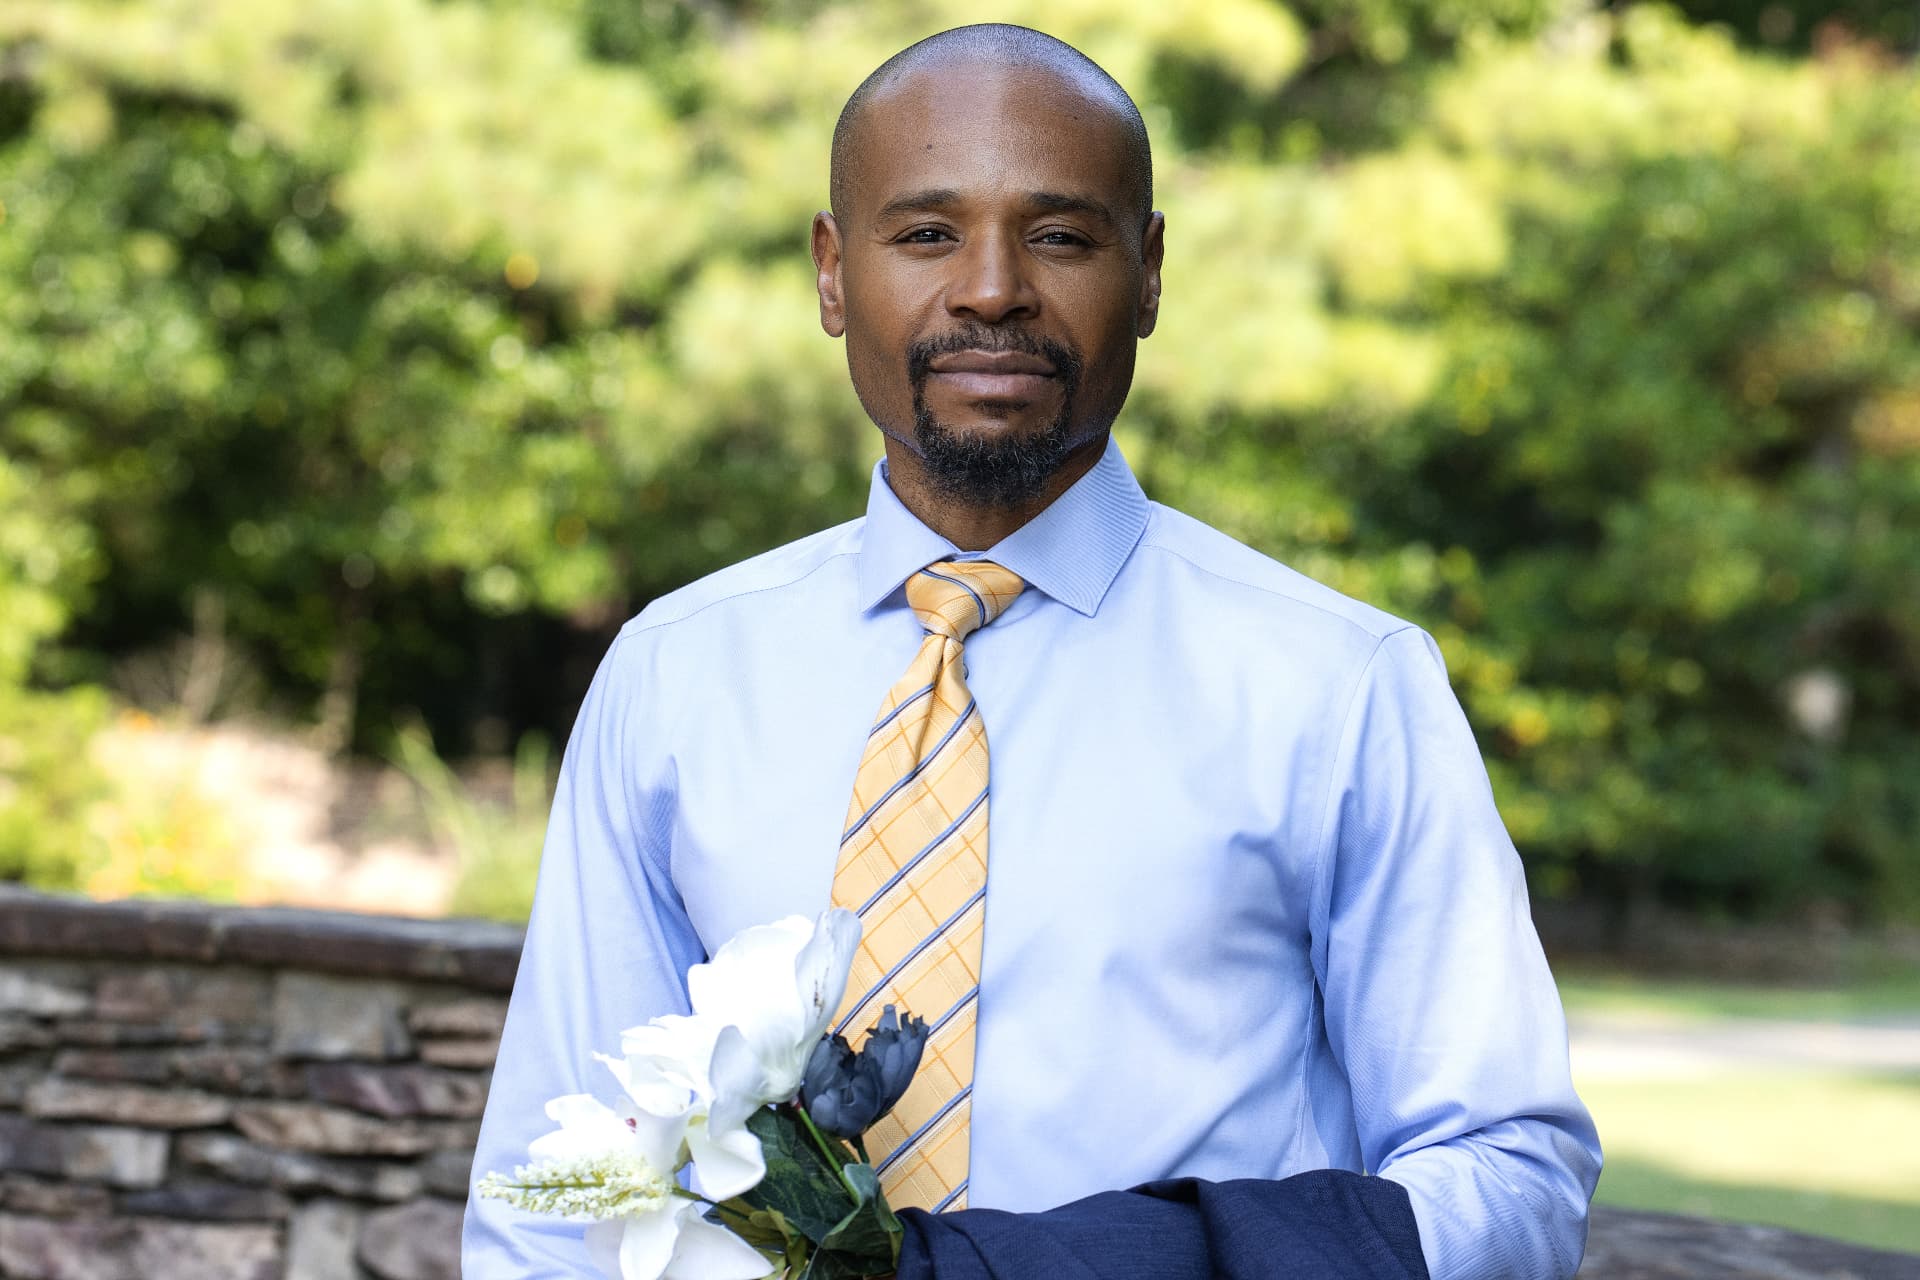
About the author
Moise (MO) Phanor
MO has spent more than a decade inside mortgage conversations — sitting with first-time buyers at kitchen tables, walking move-up families through their second or third loan, and training agents on what actually happens between offer and closing.
He wrote The Biased Buyer after noticing the same pattern over and over: the people who ended up happiest were not the ones who found the lowest rate. They were the ones who knew what they wanted before the conversation started. His work now focuses on getting that clarity to buyers earlier, through the book, workshops and keynotes.